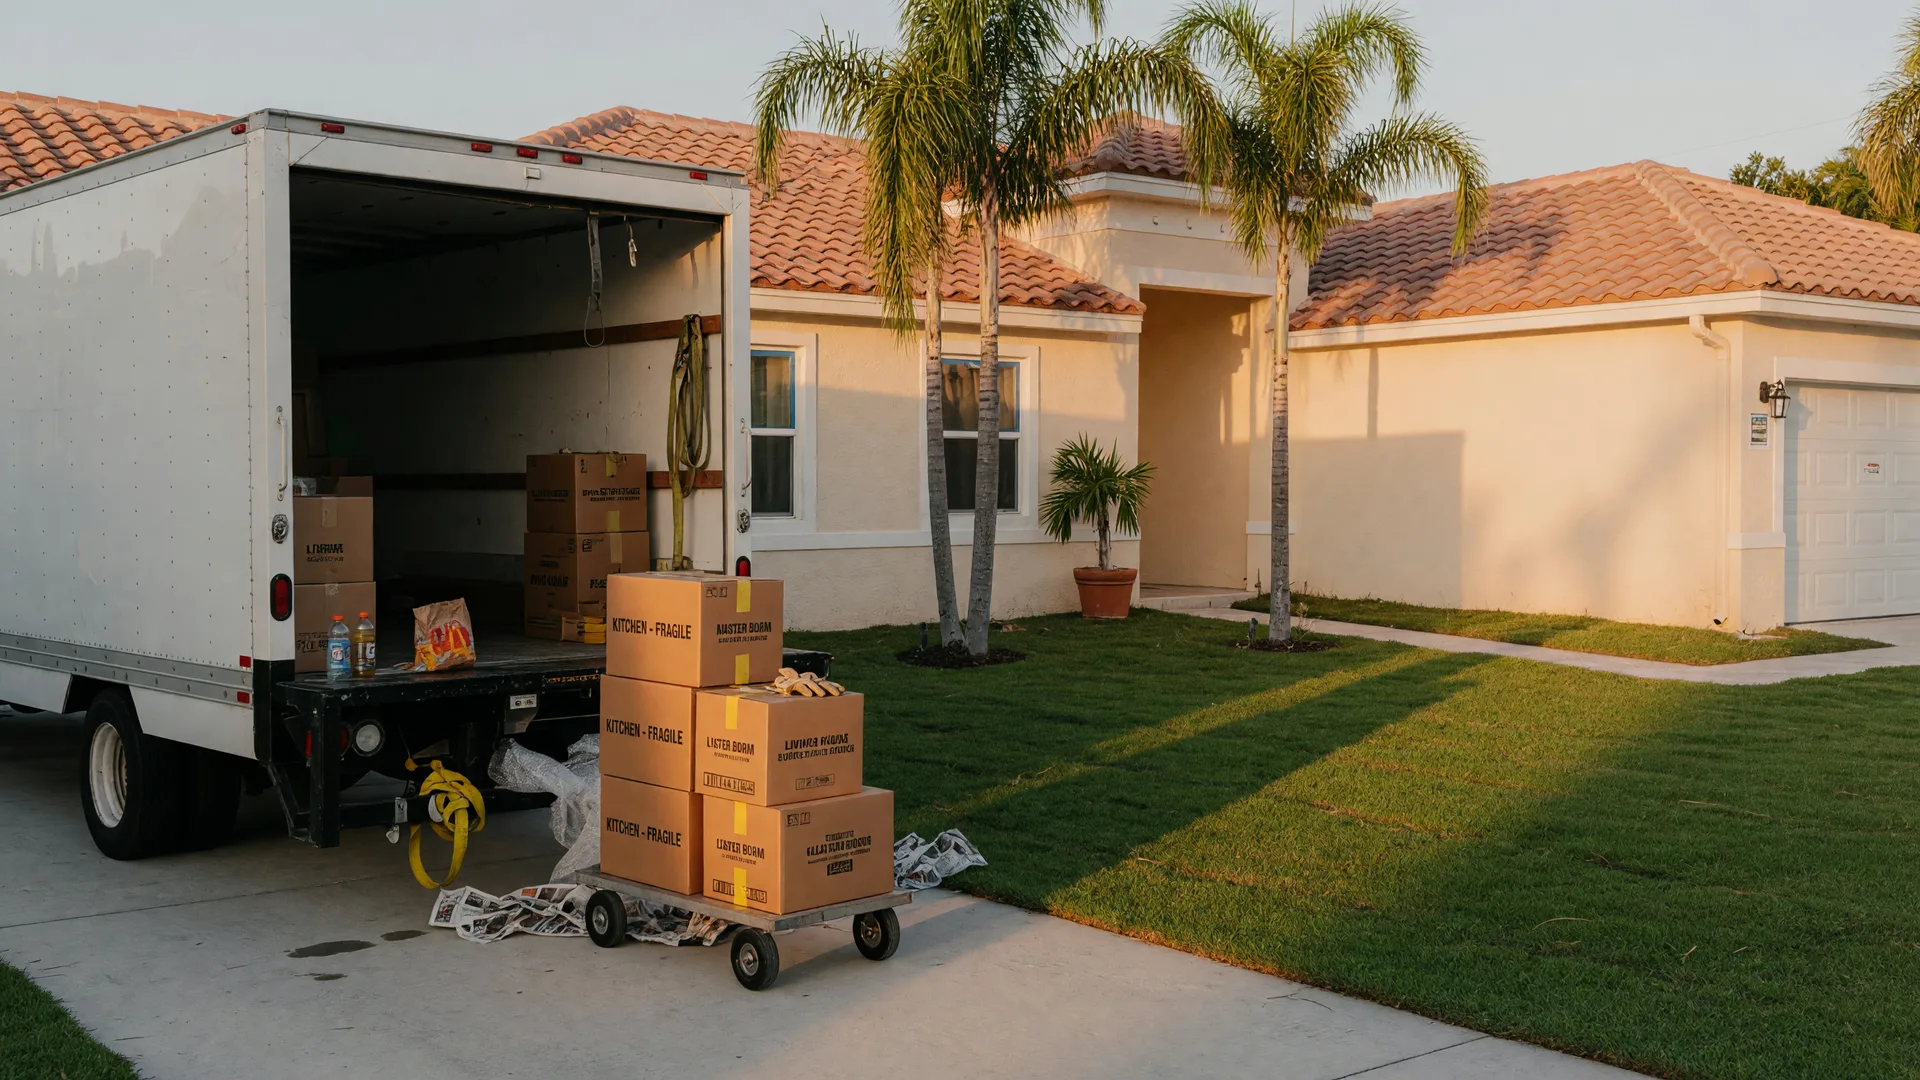
Buying a new construction home while selling your current one means coordinating two transactions on two different timelines, and one of them, the build, does not have a firm completion date. The strategies that work tend to come from three places: structuring your sale so you can stay in your home longer, using financing that does not require the sale to happen first, or combining the two. This guide explains the timing challenge, how sale contingencies work on new construction contracts and why builders view them differently, how bridge loans work, what lease-back arrangements look like, and practical ways to sequence the two transactions. It is educational context, not financial or legal advice: review your contract with a real estate attorney and talk to your lender about the options that fit your situation.
The core timing challenge
A resale purchase has a closing date that both parties can plan around, usually set in the contract and enforceable through it. A new build does not work that way. Central Florida production homes commonly take many months from contract to closing, semi-custom and custom homes take longer, and most builder contracts do not guarantee a completion date. The estimate can slip on permits, materials, weather, inspections, and the builder's backlog, so the closing can move later, and occasionally earlier.
Your home sale is a separate timeline with its own contract, its own buyer, and its own closing date, usually a matter of weeks or a couple of months after you accept an offer. If your current home sells too early, you face a housing gap before the new build is ready. If it sells too late, you risk carrying two mortgages or missing the builder's closing target and exposing your deposit. Most of the strategy in this process is about managing that gap, and most of the risk is about who absorbs the cost when the gap widens.
How sale contingencies work on new construction
A home sale contingency says the purchase is conditioned on the buyer selling their current home, usually within a specified period. On a resale, that is a normal request: the seller is another homeowner and understands the chain. On new construction, the builder is not relocating; it is selling from an inventory of homes under construction or completed homes waiting to close, and it carries the carrying costs of that inventory every month. Builders generally resist or refuse home sale contingencies for exactly that reason: a contingent buyer ties up a home the builder could sell today to a buyer who is not waiting on a sale.
In practice, most new construction contracts are written without a home sale contingency, and the builder will ask that you be pre-qualified without the sale as a condition, or that you already have an accepted offer on your home. Some builders will consider a contingency with conditions: a stronger offer, a non-refundable deposit, a shorter contingency window, or a clause that lets them keep marketing the home and sell it if another qualified buyer appears. Stances differ by builder and shift with market conditions, so the question is worth asking in writing before you sign, even if the expected answer is no.
Remember that the deposit is a real risk in this scenario. New construction deposits are commonly larger than resale earnest money, and builder contracts can make deposits non-refundable after certain milestones. If your sale falls through and you cannot close, the deposit treatment is controlled by the contract. Read those sections carefully and have your attorney review them before you sign.
Sequencing strategies that work
- Sell with a lease-back: schedule your current home's closing as close to the build's expected completion as possible, then rent your own home back from the buyer for the gap.
- Bridge loan: borrow against your current home's equity to fund the new purchase, then repay the bridge when the old home sells.
- Carry both mortgages for a window: qualify on your own income for the new home if you can absorb two payments for a while; not an option for every buyer.
- List early with a long close: some buyers will agree to a longer closing window, but usually only with a strong offer and a clear closing date.
- Rent out your current home short-term: lease it on a term that ends near the build completion, though that changes the tax treatment of a later sale and your financing, so run it past your lender and tax professional first.
Bridge loans: how they work
A bridge loan is short-term financing, typically for six to twelve months, that lets you tap your current home's equity to fund the new purchase before the old home sells. Your current home secures the loan, and when it sells, the proceeds repay the bridge along with the old mortgage balance. Bridge loans are the tool that removes the sale contingency problem: they let you close on the new build on the builder's schedule without waiting for your sale, so the builder gets a non-contingent buyer and you get the house without the gap.
Bridge loans have real costs. They carry interest on the amount borrowed, origination and appraisal fees, and the payments stack with your existing mortgage until the old home sells. Lenders underwrite them on your ability to handle the combined payments. Some bridge products combine the new mortgage and the bridge into one loan, and some lenders structure the bridge so interest accrues rather than being paid monthly. Because terms and costs vary widely by lender, this is exactly the conversation to have early, before you need the money, so the bridge is approved and ready when the builder is.
Also worth knowing: lenders generally want an estimate of your current home's value, often from an appraisal or a broker price opinion, before they lend against it, and the amount you can borrow is usually tied to your combined equity across the two homes. The stronger your equity position, the more room a bridge loan gives you to buy first and sell second.
Lease-back and rent-back arrangements
A lease-back, also called a rent-back or post-settlement occupancy agreement, is an arrangement where you sell your current home but keep living in it after closing by renting it from the buyer for a fixed period. It solves the opposite problem from a bridge loan: your old home sells before the new build is ready, and instead of moving twice or into temporary housing, you rent your own home back until the builder delivers.
Lease-backs are common but time-limited. Lender occupancy rules, state law, and insurance requirements generally cap how long a seller can remain in a home after closing as a renter, commonly around 60 days, because the buyer's mortgage terms and insurance depend on who occupies the property. The lease-back terms are written into the sales contract: the rent amount, the move-out date, and what happens if the builder is late. The rent is set at market or near it, and the buyer of your home has to agree to become a landlord for those weeks, so not every offer will accept one. Negotiate the move-out window with a cushion for build delays, and get every term in writing.
Other ways to manage the gap
If a bridge loan or a lease-back is not a fit, the remaining options are simpler and more conventional: temporary housing such as an extended-stay rental or a month-to-month apartment, or a stay with family for the weeks between closings. For sellers with flexibility, an extended closing date on the sale works when the buyer agrees. For sellers who can carry it, keeping the current home as a rental for a fixed term changes the math of the whole plan, including capital gains treatment and financing, so that path belongs in a conversation with your lender and your tax professional before you commit.
A practical sequence that often works
A common sequence for buyers: get pre-approved for the new home, including how a bridge or carrying both payments would fit; sign the new construction contract with a realistic delivery estimate and a deposit structure you can live with; list your current home when the builder's completion estimate comes into view, typically several months into the build; and set your sale's closing date with a lease-back cushion, or have a bridge loan approved, in case the build slips. Revisit the estimate with the builder at regular milestones, because the last few weeks are when timelines move most often, and keep the lender, the builder, and your agent talking to each other about the target date.
Questions to ask before you sign
- Will the builder accept a home sale contingency, and under what conditions?
- What happens to my deposit if my sale falls through before closing?
- What is the current completion estimate, and how often does the builder update it?
- Does my pre-approval cover a bridge loan or carrying two mortgages temporarily?
- What will a bridge loan cost in fees, interest, and appraisal, and how long does approval take?
- Will the buyer of my current home allow a lease-back, and how long can I stay by the lender's rules?
- What is my plan if the build is 30 to 60 days late?
Related reading on this site
Related reading on this site
- Rate locks and new build timelines: how lock terms interact with a delayed closing
- Buying new construction in Central Florida: the step-by-step
- Deposits and closing costs on new construction
- From contract to closing: the Central Florida new build timeline
- New Construction Builder Secrets: a free 31-page guide to how builders price homes
- Talk to the GPG Team about sequencing your sale and your build
Written by Tyler Gibson
Florida-licensed Realtor, team leader, and investor with 150+ transactions. Have a new-construction question this guide did not answer?